The global textile industry is experiencing a significant wave of consolidation as manufacturers worldwide confront a perfect storm of challenging market conditions. Industry data from international textile organizations reveals that companies are increasingly turning to mergers, acquisitions, and strategic partnerships to weather the current economic turbulence.
The Current State of Global Textile Markets
The textile industry, valued at hundreds of billions of dollars globally, is facing multiple headwinds simultaneously. Inflation has pushed up raw material costs, particularly for cotton, synthetic fibers, and energy-intensive processing. Meanwhile, consumer demand has become increasingly unpredictable as household budgets tighten in response to rising living costs across major markets.
Manufacturing regions from Asia to Europe and the Americas are reporting similar patterns. Order books have thinned as retailers adopt more cautious inventory strategies, having learned painful lessons from the post-pandemic overstocking that left many with unsold merchandise. This cautious approach has created a ripple effect throughout the supply chain, leaving textile manufacturers with reduced capacity utilization.
Why Consolidation is Accelerating
Several factors are driving the current consolidation trend in the textile sector:
- Economies of scale become crucial when profit margins shrink, making larger operations more viable
- Technology investments in automation and sustainable production require capital that smaller firms struggle to raise
- Negotiating power with suppliers and buyers improves significantly with greater market share
- Diversification across product lines and geographic markets helps mitigate regional downturns
- Shared infrastructure and distribution networks reduce per-unit costs
Industry analysts note that this consolidation wave differs from previous cycles. Rather than simply eliminating competition, many mergers aim to combine complementary capabilities—such as pairing traditional manufacturing expertise with digital commerce platforms or sustainable technology innovations.
Impact on Major Textile Producing Nations
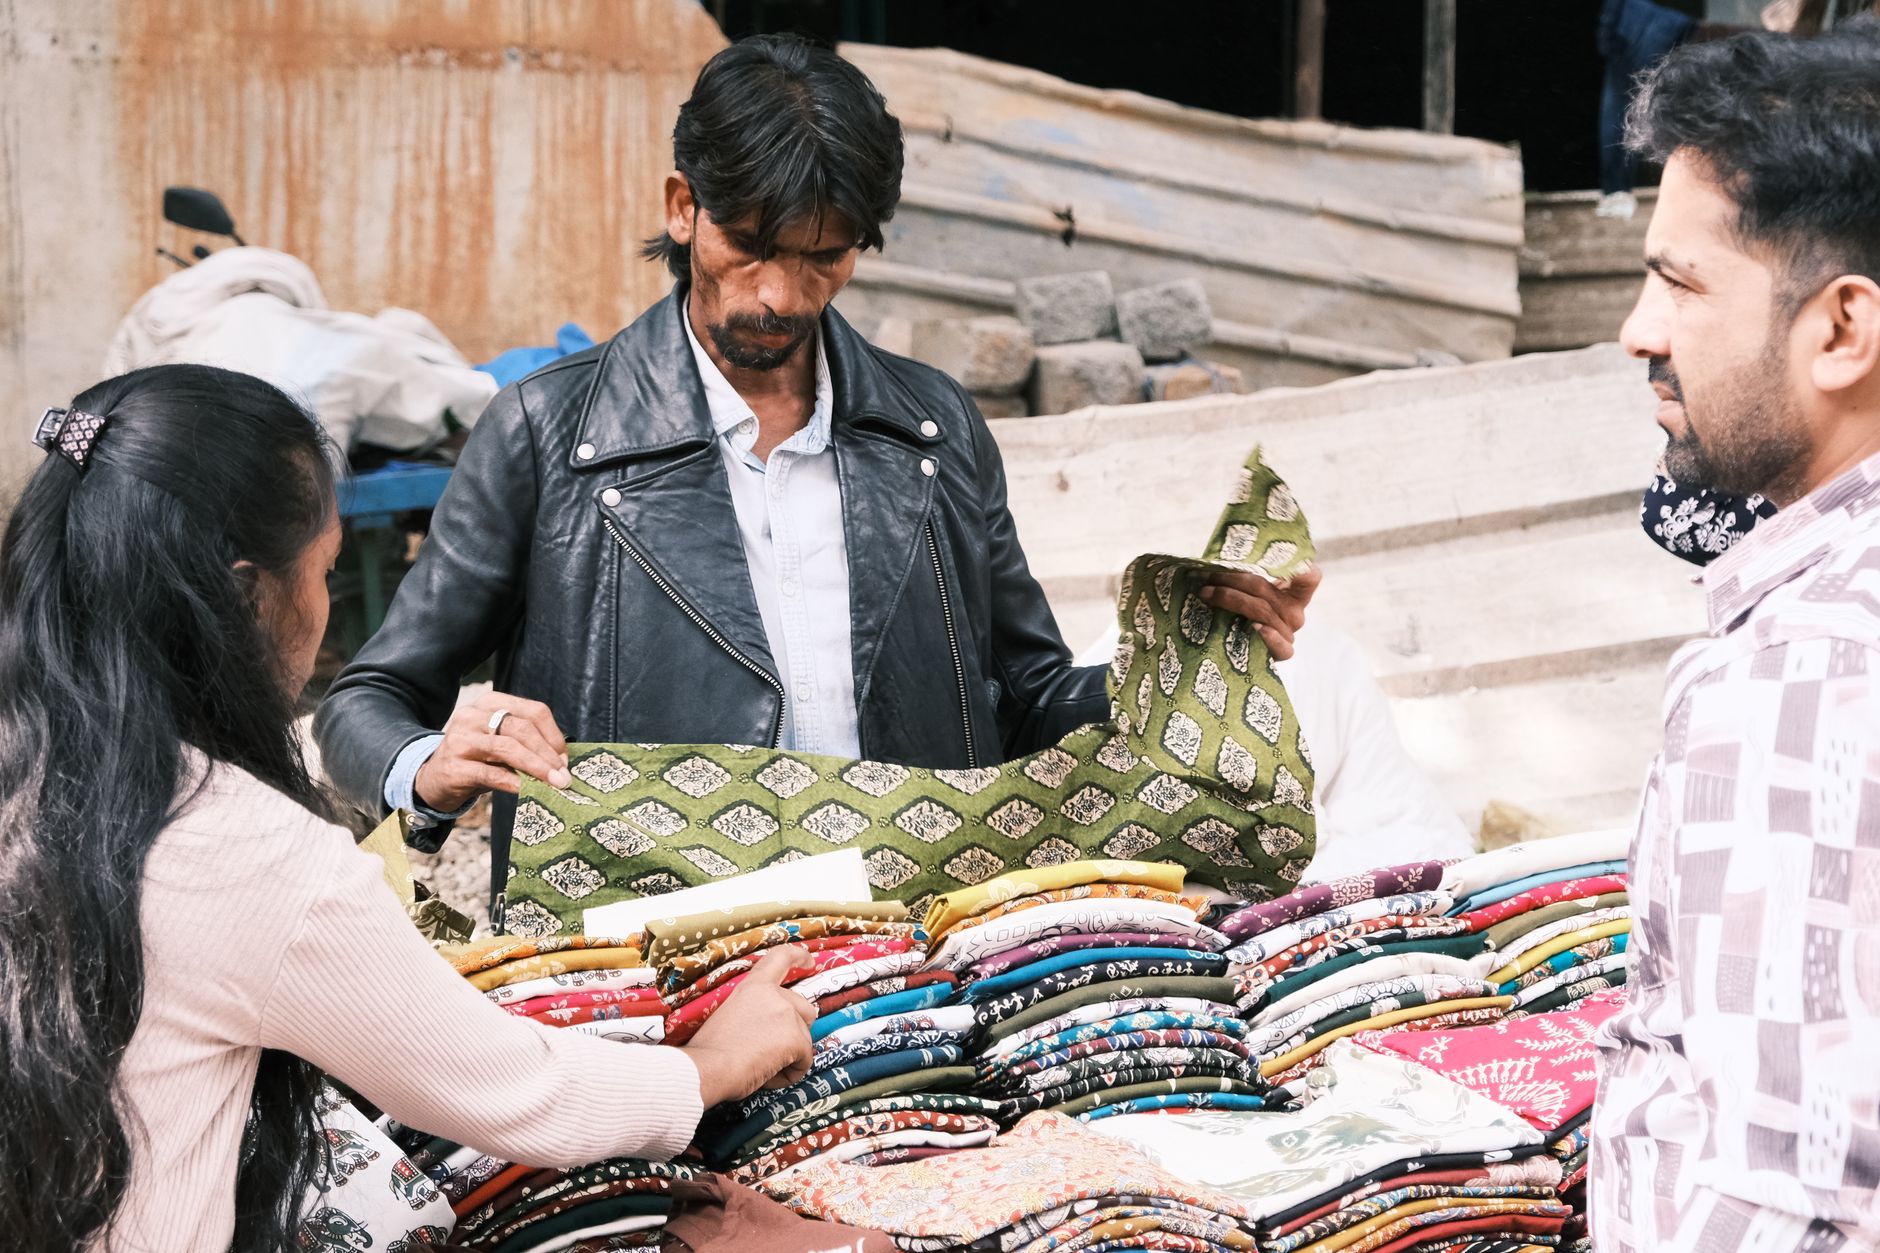
For India, the world's second-largest textile exporter, consolidation presents both opportunities and challenges. Indian textile manufacturers have traditionally been fragmented, with numerous small and medium enterprises forming the industry's backbone. The current environment may accelerate the emergence of larger, more integrated Indian textile corporations capable of competing globally on quality, sustainability, and innovation rather than cost alone.
China, despite remaining the dominant textile manufacturer, is also experiencing significant restructuring. Rising labor costs and environmental regulations have prompted Chinese manufacturers to either move up the value chain toward technical textiles and high-performance fabrics or relocate production to lower-cost countries.
Countries like Bangladesh, Vietnam, and Ethiopia—which have emerged as alternative manufacturing hubs—face a critical juncture. Consolidation among global buyers means fewer but larger purchase orders, requiring these nations to improve quality control, sustainability standards, and supply chain reliability to remain competitive.
Sustainability and Technology Driving Change
The consolidation trend is intertwined with the industry's sustainability transformation. Larger companies generally have greater resources to invest in water-efficient dyeing technologies, renewable energy, recycling infrastructure, and transparent supply chains that increasingly conscious consumers demand.
Digital transformation is another consolidation driver. Modern textile manufacturing increasingly relies on data analytics for demand forecasting, automated quality control, and optimized logistics. These technologies require substantial upfront investment that consolidated entities can better afford and utilize across broader operations.
What Lies Ahead for Textile Markets
Industry forecasters expect the consolidation trend to continue through the current economic uncertainty. However, the long-term outlook includes several potential scenarios. If global economic conditions stabilize and consumer spending rebounds, the industry could enter a growth phase where consolidated players reap the benefits of their enhanced scale and capabilities.
Alternatively, persistent economic challenges could lead to further contraction, with only the most efficient and adaptable manufacturers surviving. The wild card remains geopolitical factors, including trade policies, regional trade agreements, and sustainability regulations that could reshape global textile supply chains regardless of market conditions.
For workers in the industry, consolidation typically brings mixed outcomes. While some jobs may be eliminated through efficiency gains, larger organizations often provide better training, safer working conditions, and more stable employment than marginal smaller operations struggling to survive.
The coming months will prove critical as manufacturers navigate peak production seasons for major retail cycles. How successfully consolidated entities manage these periods will largely determine whether the current restructuring strengthens the industry or simply postpones deeper challenges.